Inflation increased again in September, and gas was not the only driver this time. The Consumer Price Index rose 0.6% for the month, the most since April, and 3.7% year over year. This is up from 3.4% in August and is higher than the 3.6% economists predicted. Core prices rose 0.3% for the month and 2.6% for the year, also above expectations. Prices are heating up as the job market cools, which makes the Fed’s next move far less straightforward.
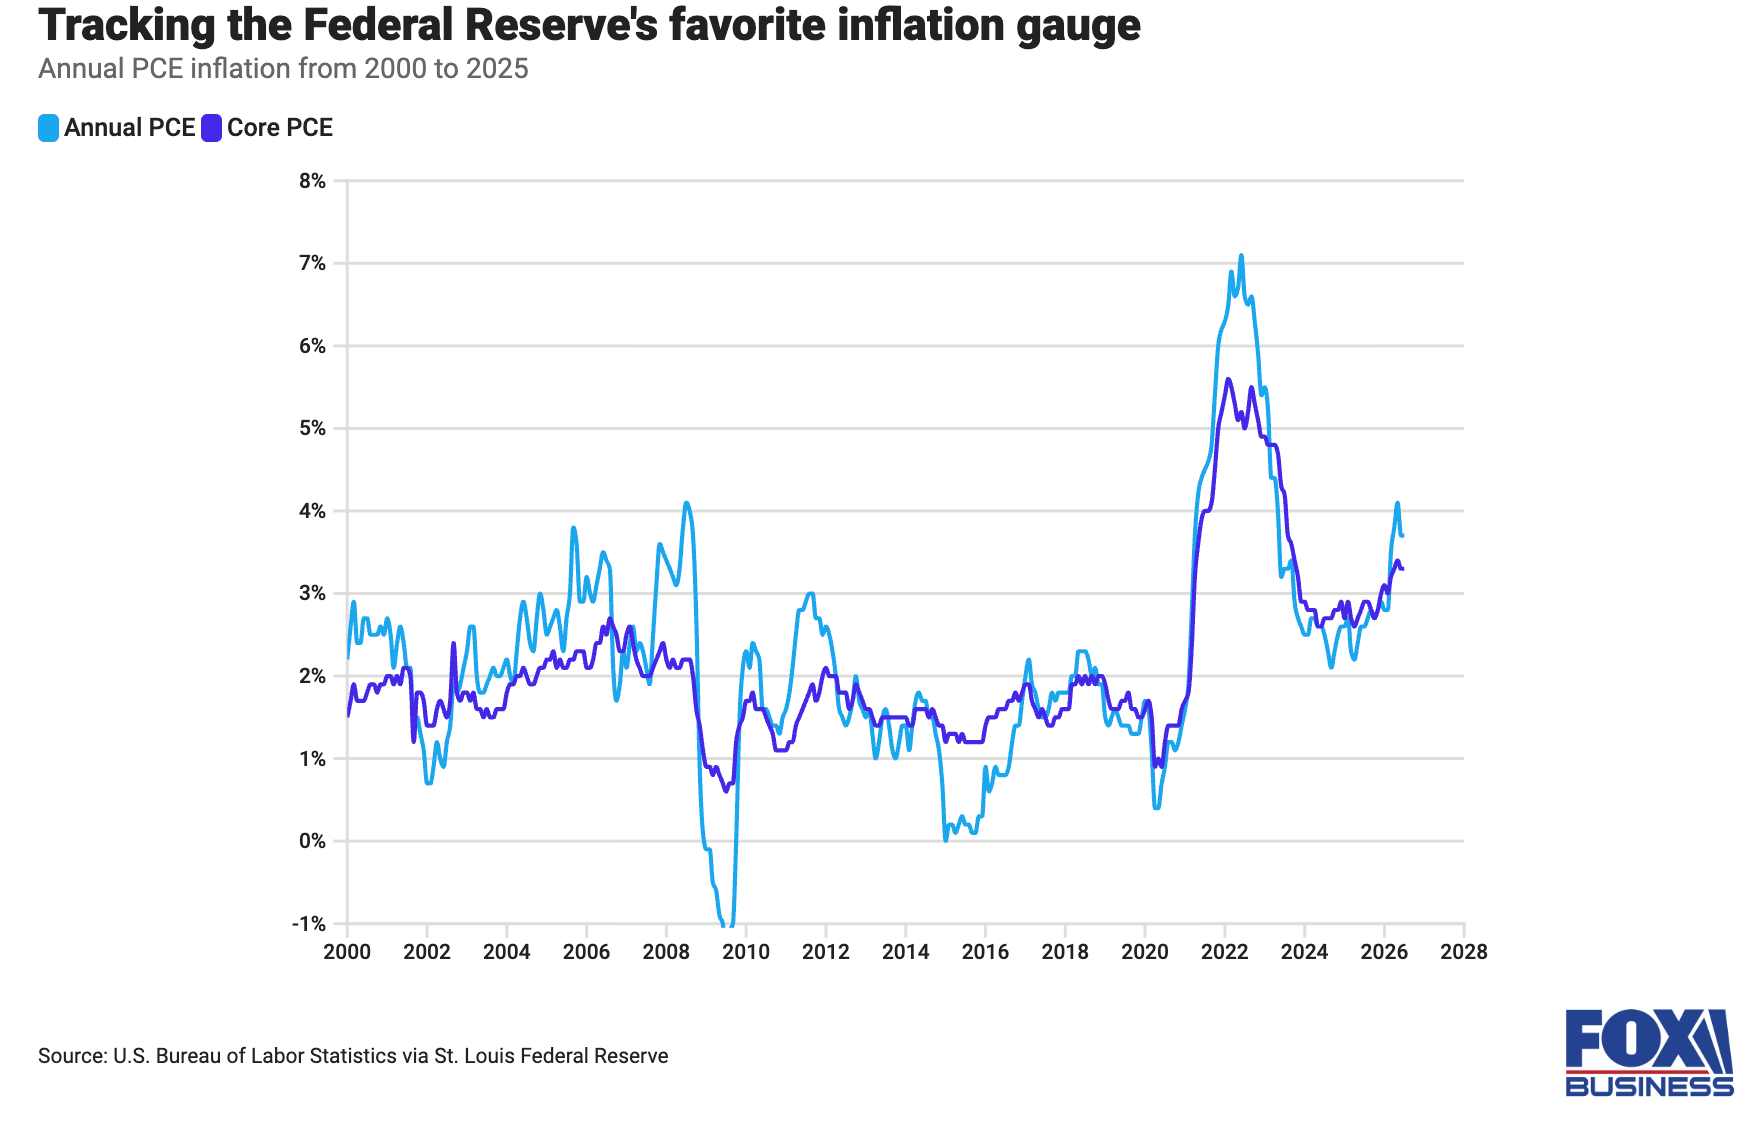
Most of the jump came from energy. Gas rose 9.1% in September alone and is up 34% from a year ago, accounting for more than half of the 0.6% increase. Overall energy prices are up about 20% over the year, driven by the war with Iran that began in February. Heating oil is up 74% over the year, and airfares are up 22% as jet fuel prices climb.
Outside of energy, the same pattern is emerging. “Supercore” inflation, which covers services excluding housing and energy, rose 0.4% in September. Over the past three months, it has been rising at an annualized rate of almost 4.6%. The AI investment boom is adding to price pressures: computer prices are up nearly 10% over the year, and software prices are up 28%. Tariffs, by contrast, have had a smaller impact than many expected. Toy prices increased, but apparel and home furnishings were almost flat. After years of skyrocketing, auto insurance premiums are now down 5% from a year ago. This spread of inflation outside of energy is what worries the Fed. Rate hikes cannot directly fix an oil shock, but they can help keep it from pushing up other prices. September’s numbers suggest this is already happening.
The labor market complicates the situation. The September jobs report showed only 29,000 jobs added, roughly a third of what was expected, and unemployment increased from 4.1% to 4.2%. This leaves the Fed with a more difficult tradeoff, since raising rates to fight inflation risks pushing more people out of work.
Meanwhile, wages are not keeping up with inflation. Real average hourly earnings fell 0.5% in September and were down 0.7% from a year earlier. They have been falling on an annual basis since April. Since January 2025, hourly earnings have risen 5.5% and prices 5.44%, meaning the average worker has seen essentially zero real wage growth. Larger paychecks buy the same amount as they did almost two years ago. With the midterms coming up, this may influence voters more than the Fed’s rate decisions.