Overview
Over the past several years, Cava (CAVA) has emerged as one of the fastest-growing names in the casual restaurant industry. Often compared to Chipotle, Cava operates a similar customizable model but focuses on Mediterranean-inspired bowls, pitas, dips, and salads. The company has built its brand around healthier ingredients, convenience, and customization, helping it appeal particularly well to younger consumers.
Investment Thesis
Cava’s recent growth has been notable. In its most recent quarter, revenue increased 31.3% year over year to $365.4 million, with same-restaurant sales also growing 9.0%. This growth wasn’t driven solely by higher prices, as guest traffic increased 5.3%, suggesting more customers are visiting Cava restaurants. The company also opened 17 new locations during the quarter, bringing its total to 476 restaurants; nearly 20% more than the year prior.
The most exciting part of Cava’s story may be how much room the company still has to expand. Unlike Chipotle and other established casual chains with thousands of locations, Cava remains relatively early in its national expansion. The company expects to open 75 to 77 new restaurants during 2026, while recent openings have continued to perform above management’s expectations.
Cava is also showing that its expansion can translate into higher earnings, not growth at any cost. Adjusted EBITDA increased 30% year over year to $54.7 million during the second quarter, while net income reached $23 million.
The biggest concern is valuation. Investors already recognize Cava’s growth potential, meaning the company must continue delivering strong restaurant openings, traffic growth, and profitability to meet expectations. Restaurant profit margin also declined slightly from 26.3% to 25.7% in the latest quarter as Cava faced higher costs from wages, delivery, and new menu offerings.
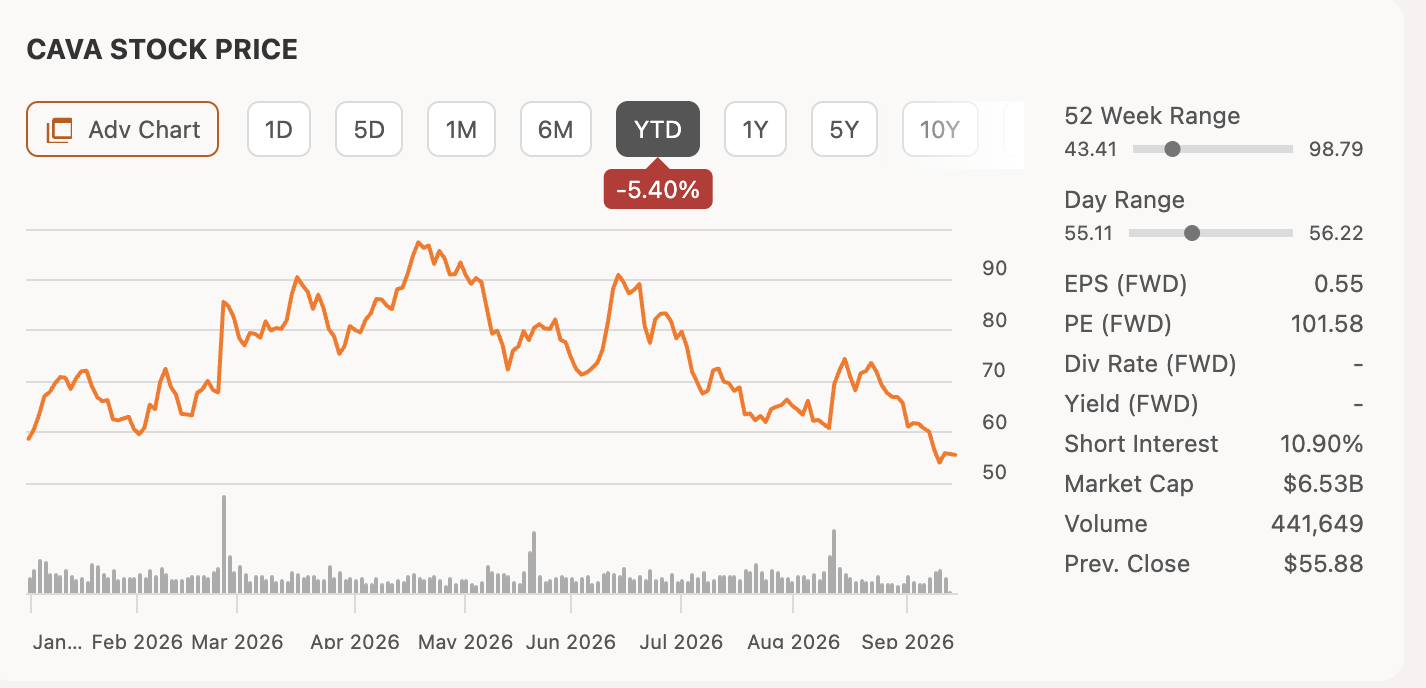
Cava YTD Performance (Seeking Alpha)
Why to Buy
Despite these risks, Cava’s combination of strong same-store sales, growing customer traffic, rapid restaurant expansion, and improving earnings makes it an attractive long-term growth story. If Cava can continue successfully expanding across the country, the company has an opportunity to become one of the next major national casual restaurant brands.